From:Jinggong Technology Publication date: 2018-05-09
May 03, 2018 Source: Carbon Fiber Research Society
Recently, the Internet is full of comments on the "chip pain". Of course, the pain of "chip" is mainly the problem encountered by the electronics industry, but there are still many similar core technologies. The ban on chips only reminds people not to use it as a case. Nor is it that only military products can be the object of embargoes, even if the core technology of civilian use can still be resolved without complying with the rules of the market economy and without the rules of international trade. Because China is a rising power, it will inevitably have a conflict of interest with the United States in the process of economic development. Don’t always use ideology to say things (as some people say on the Internet), when it comes to the interests of both countries, The ban will happen at any time, even if the Chinese company can find the reason to punish you.
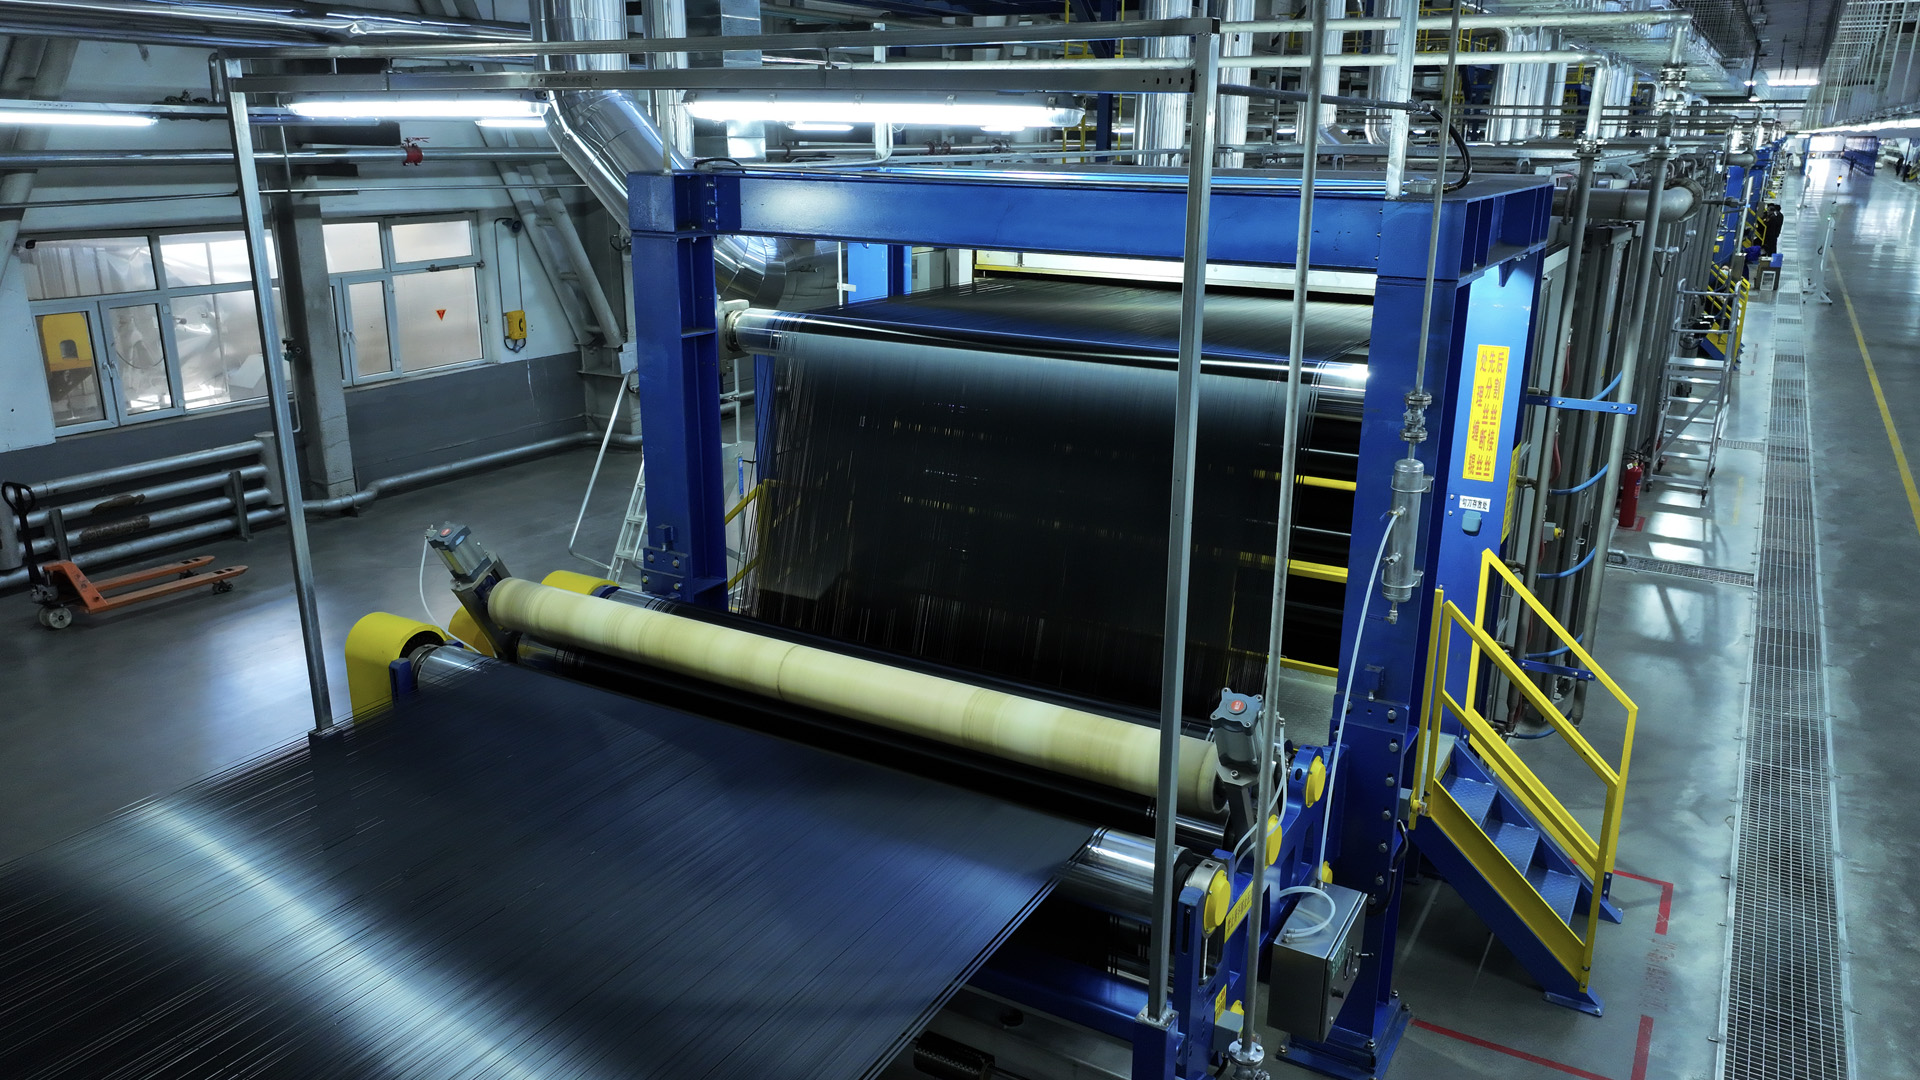
Carbon fiber is another key core material in the country after the "chip" incident. Therefore, how to achieve carbon fiber localization (including military and civilian use) is also the focus of everyone's discussion. I have been working in the field of carbon fiber for nearly 40 years. I have been using it in the domestic carbon fiber industry for 7 years. I would like to talk about the road to industrialization of domestic carbon fiber in conjunction with the road of industrialization of Dongli carbon fiber.
The application of carbon fiber in military equipment is well known. The same carbon fiber and its potential applications in the industrial field (including civil aviation aircraft, rail transit and automobiles) will certainly be the key core technology. The amount of 10,000 tons in the future is not an idiotic dream. Of course, it will be 10-20 years later in China, but how is domestic carbon fiber enterprise a key factor during this period? If nothing is done, the application of tens of tons of 10,000 tons will be the world of foreign carbon fiber manufacturers, and the pain of similar "chips" will reappear; if it is to get this market, how will domestic carbon fiber enterprises survive at least 10 years? The hardship and long road of carbon fiber industrialization is also a common problem for all similar core technologies to achieve industrialization. The country can invest hundreds of billions for two bombs and one big aircraft, but how to develop a huge demand for core technology to achieve industrialization process The corresponding policies for the amount of investment require a good strategy for people of insight.
The industrialization of carbon fiber is inseparable from the understanding of the international carbon fiber overlord Dongli industrialization. Toray's carbon fiber road started in 1970. Toray's carbon fiber mass production (ten tons) started in mass production of fishing rods and golf clubs. In 1975, the application of carbon fiber in Boeing 737 load-bearing structure was realized. It promoted the mass production of Toray's 1,000-ton class. In the 1990s, the 50% weight of the Boeing 787's body structure used carbon fiber to promote the mass production of Dongli 10,000-ton, and at the same time realized the transition from long-term loss to stable profit. Faced with the demand for lightweight in the automotive sector, Toray is advancing toward the goal of 100,000 tons by acquiring Zoltek.
Toray's industrialization path has always been closely tied to Boeing. The development of carbon fiber is inseparable from the mass production of Boeing aircraft composite structures. In the development process of Toray in the past few decades, the so-called first-generation carbon fiber T300 index was proposed and realized to meet the needs of Boeing. The second-generation carbon fiber T800 index was proposed by Boeing by Toray, and the third. The indicator of the T1100 is also proposed by Boeing and realized by Toray. T1000, which everyone praised on the Internet, Dongli has been researched and developed in 1986, but it has rarely been applied so far. This shows that the materials department has no industrialization prospects. It is also important to note that Toray has not only developed carbon fiber that meets the needs of the industrial sector, but also developed epoxy resin 5208 for Boeing secondary bearing components and toughened epoxy resin 3901 for Boeing main bearing components. And the corresponding prepreg, while Toray has hundreds of technicians stationed in Boeing, in conjunction with Boeing to achieve carbon fiber applications, assisting Boeing to develop design methods and production processes for manufacturing aircraft carbon fiber composite parts. From the industrialization of Toray carbon fiber, we can find:
1. In the 1970s, Toray's T300 performance was not as good as the current domestic carbon fiber, but even the aircraft parts made with it were safely used for decades. However, the reason why the Toray T300 is better than the current domestic carbon fiber is through long-term. The use and production of continuous improvement in performance and continuous cost reduction results.
2. Toray can realize the industrialization of carbon fiber, not only to develop the carbon fiber of the required performance according to the needs of downstream customers Boeing, but also to provide the resin (prediction and cost) and its prepreg with matching performance (including cost and processability). In Boeing, hundreds of technicians have been working with Boeing for a long time, and developed a process suitable for manufacturing parts to achieve mass production of composite parts that meet the requirements of use, thereby obtaining rich profits by supplying prepregs in large quantities.
3. Toray has been producing carbon fiber production for a stable profit for more than 30 years, which means that the chairman of Toray (carbon fiber is only a small part of Toray Group) has sufficient financial resources to withstand long-term losses and to withstand the outside world. The ability to stress (including board members).
4. The industrialization road of Dongli carbon fiber (or stable profit) is realized simultaneously with the mass production of Boeing civil aircraft composite material structure (50% of the weight of the structural structure).
The industrialization of Toray carbon fiber has given us a very important inspiration: that the domestic carbon fiber industrialization must be realized simultaneously with the mass production of composite materials in the industrial field.
The domestic carbon fiber started with Dongli basically, and has not paid attention to the development of the corresponding products, so it has been stuck in a state of misconduct for a long time. In the 1970s and early 1980s, domestic military aircraft began to use carbon fiber composite materials on military aircraft. It was only a trial, China's first aircraft structural component - strong 5 inlet siding (December 28, 1977) The test flight was successful, and on this basis, the development of military composite composite tails began. During this period, Toray's T300-3k carbon fiber can always be easily obtained from abnormal channels (although the “Batu” agreement for the implementation of the carbon fiber embargo in China has always existed), domestic carbon fiber has always been untouched, and all military composite parts are Both use Toray's T300 carbon fiber.
Until the beginning of this century, the T300 imported from abnormal channels suddenly disappeared from the market. The market price of T300-3k soared to 8,000 yuan/kg. There is still no market (which may be related to the international situation at the time), which directly threatens China. In this context, we began to realize the importance of localization of carbon fiber and started the climax of localization of carbon fiber. In this round of carbon fiber localization boom, dozens of carbon fiber enterprises have emerged in China, but Breaking through the long-term cost of carbon fiber technology, only a few private enterprises (both experienced long-term investment and losses of about 10 years) stood out and achieved the localization of carbon fiber supply for military equipment.
However, this round of localization only solves the localization of military carbon fiber. Although some carbon fiber enterprises can rely on the high price of a small number of military products to achieve profitable operation, it does not really solve the problem of industrialization of the domestic carbon fiber industry (military carbon fiber consumption only 100 tons), far from the goal of achieving stable and long-term survival. Therefore, it is still necessary to explore the industrialization of domestic carbon fiber, and Dongli's industrialization road should be a model worth learning from, but at the same time, we must be aware of the differences between the domestic carbon fiber enterprises and Dongli's environment:
1. Toray was at the same level as other carbon fiber companies in the 1970s, while domestic carbon fiber companies are currently facing strong rivals such as Toray, Hex, Dongbang and Mitsubishi. Unlike Boeing at the time, it was the best choice among suppliers with similar technical strengths. At present, downstream users can prefer powerful foreign suppliers. The industrialization of downstream industrial carbon fiber composite products can be achieved by using foreign high-quality carbon fiber. In this context, domestic carbon fiber companies must be aware of the laws of the market economy.
2. The domestic carbon fiber industrialization road is different from the industrial field that Dongli faces. Dongli is faced with a Boeing aircraft structure that has an urgent need for lightweighting. It has a high cost tolerance and a military composite structure. At the same time, the Boeing series has a variety of models, all of which have been mass-produced. In particular, the Boeing 787 has a structural weight of 50% using carbon fiber composite materials. Currently, the annual demand for carbon fiber can reach 10,000 tons. The domestically produced large aircraft facing domestic carbon fiber are mainly C919 and CR929. The batch production is still waiting for a long time, and the dosage is limited. Even after 10 years, it is only on the order of thousands of tons. Individual enterprises can aim at this, but it should not be A huge market for domestic carbon fiber. Therefore, domestic carbon fiber industrialization must choose other industrial fields.
At present, other industrial fields that have been widely used in China are mainly sports, leisure and building reinforcement. Wind turbine blades and pressure vessels are two other industries that are growing rapidly. The former is basically saturated, and the latter's raw materials and technologies are basically stereotyped. Carbon fiber entering these industries can basically only compete with foreign carbon fiber companies. Unless domestic carbon fiber has a revolutionary breakthrough in carbon fiber production technology, it is possible to occupy the market with performance and price superior to foreign carbon fiber, and this is not in line with domestic carbon fiber. The status quo is also not conducive to the survival of domestic carbon fiber enterprises. Therefore, the carbon fiber composite material must realize a new way of industrialization of domestic carbon fiber, and select a new industrial field that has not yet used carbon fiber in large quantities, and may be used in large quantities.
According to the needs of China Manufacturing 2025, the most promising areas should be the application of transportation vehicles, including railroad crossings and automobiles. These industries are different from civil aircraft. Civil aircraft customers usually have the basis of military aircraft, and the understanding of carbon fiber composite materials in these industries is basically zero. At the same time, the urgency of using carbon fiber for lightweighting is far less than that of civil aircraft. The civil aircraft is to discuss lightweighting based on the use of the lightest aluminum, which is based on the use of steel to discuss lightweight, in addition to carbon fiber. There are many other options. Therefore, while learning from the Toray model, we must realize that domestic carbon fiber companies must provide more comprehensive technical support to downstream users, and in view of the acceptability of these fields, the existing composite technology foundation must be revolutionized. Innovation.
In this context, where is the way out for domestic carbon fiber companies? The concept of “Full Industry Chain Carbon Fiber Enterprise” when Mr. Qian Yunbao founded Hengshen Company is worthy of reference by carbon fiber peers. That is, Hengshen Company is not only a carbon fiber production enterprise, but also provides carbon fiber (including fabric)-intermediate products (resin and Prepreg)—Composite product development technology services (including design analysis, molding process and manufacturing), one-stop service of the entire industry chain carbon fiber enterprises. The advantage of this is that, under the premise that the customer has the demand but not the ability, the carbon fiber with poor performance produced by the company is used to provide the prepreg raw material that meets the user's demand, and finally develops to meet the user's requirements through independent design and process. It can realize the batch production of composite materials. Once the batch production of composite products is realized, the carbon fiber produced by the enterprise can be guaranteed to be sold in large quantities, and the large-scale production and sales of carbon fiber produced by the enterprise can be realized while realizing the industrialization of composite materials for users. At the same time, the carbon fiber quality of the company is continuously improved during production and use.
The 10-year practice of Hengshen has initially witnessed the correctness of this concept. The best example is the world's first 19-meter-long all-carbon fiber composite subway car developed by Hengshen and Changke. Of course, Qian Yunbao’s idea was once regarded as a Don Quixote-style joke. It is indeed more expensive than simply producing carbon fiber. It takes a long time and the difficulty is not a little bit, but it has indeed seen the dawn of success. Unfortunately, Qian Yunbao The young man died young and did not see the realization of the god of death, but his attempt was a valuable asset that future generations could learn from.
The concept of Hengshen's entire industrial chain is difficult to replicate. After all, he only relies on his own efforts to do things for the country and the entire industry. Only individuals like Qian Yunbao can do it, but his concept should be It has been promoted in other forms, and it is gratifying that this concept has been accepted by more and more entrepreneurs from the disclosure of various information released by the carbon fiber industry.
In short, the industrialization of domestic carbon fiber has the following two points worthy of attention:
1. In either form, domestic carbon fiber enterprises must have a full industrial chain and strong capital. They can be industrialized in the form of alliances between carbon fiber enterprises and downstream users in the whole industry chain, or led by downstream users including carbon fiber, resin, and prepreg. Close cooperation of materials, design analysis, composite parts production, production equipment and other enterprises to achieve a win-win enterprise chain of the whole industry chain, while realizing the mass production of composite products (components or industrial products) in an industrial field The realization of domestic carbon fiber industrialization will enable carbon fiber enterprises to achieve long-term profitability.
2. It must be realized that the realization of domestic carbon fiber industrialization must be a business that requires at least 10 years of long and costly long-term losses. Only a group of companies with long-term financial strength can be qualified.
Address:No. 1809, Jianhu Road, Keqiao District, Shaoxing City, Zhejiang Province
Tel:0575-8488 6688
Fax:0575-8413 8800
Email:office@jgtec.com.cn
Copyright © 2026 Zhejiang Jinggong Integrated Technology Co., Ltd 浙ICP备14023678号-1
 浙公网安备 33060302000366号
Technical Support:yushangweb